

What happened to mortgage rates this week?
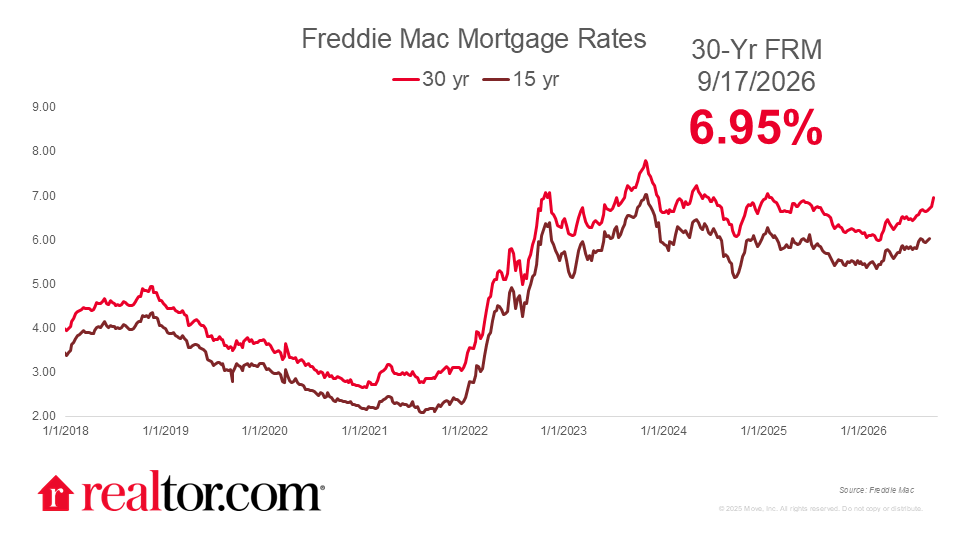
The Freddie Mac 30-year fixed mortgage rate climbed 8 basis points to 7.03% this week, the first reading above 7% since January 2025. Rates entered the week just 5 basis points below that line after jumping 19 basis points to 6.95%, the largest one-week move since April 2025. The 10-year Treasury yield drove most of that increase and has kept climbing, with inflationary pressure building and Brent crude oil prices hovering above $100 per barrel again. With the 10-year Treasury surging 15 bps on Wednesday, to 5.11 percent, a 19-year high, upward mortgage rate pressure seems likely to linger.
The FOMC raised the federal funds rate by a quarter point last week to a range of 3.75 to 4.00 percent, and the messaging since has leaned hawkish. In remarks at the Chicago Fed’s housing affordability summit, Governor Michael S. Barr acknowledged his support for the unanimous decision to hike. He argued the Fed had been “out of position” given changes in the economy, and said his base case is that “further policy adjustments are likely to be needed to bring inflation back to target in a timely fashion”. Barr also noted that roughly half of outstanding mortgages still carry a rate of 4% or below, which keeps existing owners locked in place. Realtor.com research shows that lock-ins remain a dominant force within housing, and the current mortgage rate environment adds to these dynamics at play.

What does this mean for the housing market?
For buyers and sellers, the highest mortgage rates in more than a year and a half are landing on a market that is in the midst of a slowdown. Existing home sales hit their 2026 low in August and pending sales have turned negative year over year. A 7% handle is as much psychological as mathematical, and it arrives at the point in the season when leverage usually shifts toward buyers.
For buyers, the practical response is to build the range into the budget rather than react to each weekly print: our analysis of mortgage rate volatility since 2000 finds that buyers three months out from closing should plan for 50 basis points of movement in either direction, meaning anything between roughly 6.5% and 7.5% from here, a swing worth roughly $30,000 in purchasing power on a $2,000 monthly principal and interest budget. For sellers, the question is still whether to cut prices as a greater share have recently done or pull the listing. Either way, this will continue to add to the headwinds in place for home sales.